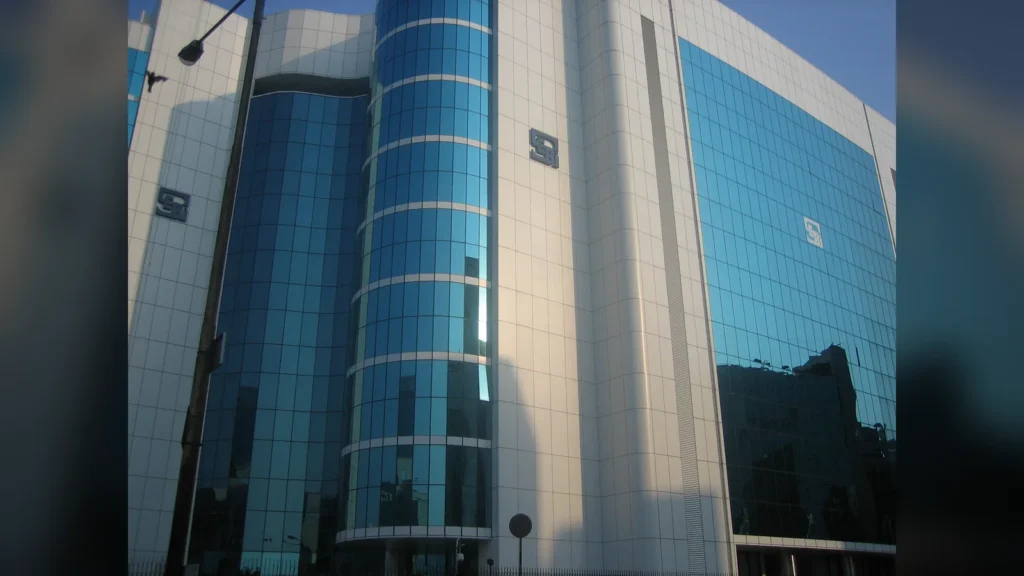
NEW DELHI — The Securities and Exchange Board of India (SEBI) is reviewing a proposal that would permit stock exchanges to list their own securities on the platforms they operate. The move has drawn criticism from market participants who warn of a conflict of interest, while regulators argue the model could streamline capital‑raising for exchanges.
Regulatory rationale
SEBI officials say the self‑listing framework is intended to broaden capital‑market depth and provide exchanges with an additional source of funding for technology upgrades and market‑infrastructure projects. The board’s draft guidelines, circulated to market participants in early September, outline eligibility criteria, disclosure requirements and a supervisory mechanism designed to prevent undue influence over listed securities.
Industry pushback
Industry leaders have voiced reservations about the proposal. The National Stock Exchange (NSE) chairman, in an interview reported by Business Standard on 25 September 2026, urged a reconsideration of self‑listing, citing the potential for “regulatory capture” and the difficulty of maintaining an arm’s‑length relationship when an exchange is both regulator and listed entity.
Other exchanges and broker‑age firms have echoed similar concerns, arguing that the model could erode investor confidence if market participants perceive that listed exchanges enjoy preferential treatment in trading, fee structures or corporate actions.
SEBI’s conflict‑of‑interest safeguards
In response, SEBI officials highlighted a series of safeguards embedded in the draft. The board proposes that any exchange seeking to list must obtain prior approval from an independent committee comprising members from the Ministry of Finance, the Reserve Bank of India and senior officials from SEBI itself. The committee would assess the exchange’s governance standards, audit reports and compliance history before granting a listing permit.
SEBI also plans to impose a mandatory lock‑up period of 12 months on the exchange’s own shares, during which the entity cannot engage in share‑buyback or dividend distribution without explicit board approval. Additionally, the regulator intends to subject self‑listed exchanges to heightened surveillance, including quarterly reporting of order‑flow data and transaction‑level disclosures to the market watchdog.
तुलनात्मक दृष्टिकोण
स्व-सूचीकरण (Self-listing) वैश्विक स्तर पर अप्रतिद्धुत नहीं है। यूनाइटेड किंगडम की लंदन स्टॉक एक्सचेंज और जापान की टोक्यो स्टॉक एक्सचेंज ने अपनी सहायक कंपनियों (subsidiaries) को सूचीबद्ध किया है, हालांकि दोनों अलग-अलग कॉर्पोरेट संरचनाओं के तहत संचालित होती हैं और भिन्न नियामक निगरानी के अधीन हैं। सिक्योरिटीज एंड एक्सचेंज बोर्ड ऑफ इंडिया (SEBI) के प्रारंभिक प्रस्ताव में इन पूर्वोक्त उदाहरणों का उल्लेख करते हुए यह जोर दिया गया है कि भारत की बाजार संरचना भिन्न है, जिससे प्रणालीगत जोखिम (systemic risk) को कम करने के लिए एक “संरक्षक नियामक मॉडल” (conservative regulatory model) की आवश्यकता होती है।
बाजार गतिशीलता पर संभावित प्रभाव
विश्लेषकों का कहना है कि यदि इस प्रस्ताव को स्वीकृत किया जाता है, तो एक्सचेंजों को नए ट्रेडिंग प्लेटफॉर्म, डेटा-एनालिटिक्स टूल्स और क्रॉस-बॉर्डर कनेक्टिविटी में निवेश के लिए पूंजी का मुक्त होना संभव हो सकता है। हालांकि, वे चेतावनी देते हैं कि यदि सूचीबद्ध इकाइयों को मार्केट-मेकिंग सेवाओं में प्राथमिकता प्राप्त पहुंच या कम लेनदेन शुल्क दिया जाता है, तो एक्सचेंजों के बीच प्रतिस्पर्धा में विकृति उत्पन्न हो सकती है।
निवेशक समूहों ने पारदर्शी सार्वजनिक परामर्श प्रक्रिया की मांग की है। सिक्योरिटीज इंडस्ट्री डेवलपमेंट काउंसिल (SIDC) ने SEBI को टिप्पणी अवधि को 30 दिनों के लिए बढ़ाने की औपचारिक अनुरोध जमा किया है, जिसमें प्रस्तावित निगरानी समिति की संरचना और हितों के टकराव (conflicts of interest) का मूल्यांकन करने के मानदंडों की स्पष्टता की मांग की गई है।
आगामी चरण
SEBI ने मुंबई में 10 अक्टूबर 2026 को हितधारकों की बैठक निर्धारित की है, जहां प्रारंभिक दिशानिर्देशों पर विस्तृत चर्चा की जाएगी। नियामक प्राधिकरण ने संकेत दिया है कि परामर्श प्रक्रिया के परिणामों के अधीन, अंतिम नीति चौथे तिमाही के अंत तक जारी की जा सकती है।
इसके तक, बाजार के भागीदारों से अपेक्षा की जा रही है कि वे नियामक चर्चा का गंभीरता से पालन करें, क्योंकि यह निर्णय भारत के पूंजी बाजारों के शासन ढांचे (governance framework) को आने वाले वर्षों के लिए आकार देगा।